By Gaurav Sharma | Updated September 2026 | Cost figures are drawn from the CareScout/Genworth 2025 Cost of Care Survey (published in 2026). Veterans benefit figures reflect the VA pension rates effective December 1, 2025.
Please note: This guide is for general education and budgeting. It is not legal, tax, medical, or financial advice. Care prices and benefit rules vary by state and by provider, so always get written quotes from local agencies and confirm eligibility with official sources such as VA.gov and Medicare.gov.
The cost of in-home care for seniors is one of the first things families worry about when a parent needs help at home. Most older adults want to stay in their own house, around familiar things, for as long as they safely can. Professionals call this “aging in place.” For many families it starts the day Mom has trouble getting in and out of the shower, or Dad stops cooking real meals.
That is usually when the big question lands: how much does a caregiver cost, and how do we pay for it?
This guide walks through current national numbers, explains why quotes differ so much, and covers the programs that can actually help. If you are sorting this out for someone you love, take a breath. You do not have to solve it all in one afternoon.
Two Types of In-Home Care (They Are Not the Same)
Many families mix these up, and it is the most common budgeting mistake.
1. Non-medical personal care. This is help with everyday life: bathing, dressing, meals, light housekeeping, medication reminders, companionship, and rides to appointments. The caregiver is a home care aide, and no nursing license is required. This is what most families need first.
2. Home health care (skilled care). This is provided by licensed nurses or therapists and covers things like wound care, injections, and physical therapy. It is usually ordered by a doctor after a hospital stay, surgery, or illness.
Most families begin with personal care and add skilled visits only when a doctor recommends them.
What Does In-Home Care Cost?
The CareScout/Genworth 2025 Cost of Care Survey puts the national median for non-medical in-home care at about $35 per hour, up roughly 3% from the year before. At 44 hours a week, that works out to about $80,000 a year.
Local prices vary a lot. Some Southern states come in around the mid-$20s per hour, while parts of the West Coast, Northeast, and Pacific Northwest can top $40.
Here is what that national median looks like as a monthly budget:
| Care level | Per month | Per year |
|---|---|---|
| 10 hrs/week (respite, errands) | ~$1,500 | ~$18,000 |
| 20 hrs/week (morning routine help) | ~$3,000 | ~$36,000 |
| 40–44 hrs/week (full workday coverage) | ~$6,100–$6,700 | ~$73,000–$80,000 |
| 24/7 care (around the clock) | ~$12,000–$25,000+ | ~$145,000–$300,000+ |
Based on a $35 hourly rate. Your local agency quote is the only number that really counts.
Quick formula: hourly rate × hours per week × 4.33 = monthly cost.
Why 24/7 Care Has Such a Wide Range
If you paid $35 an hour for all 168 hours in a week, the bill would be roughly $25,000 a month. That is the high end of the table. The low end reflects live-in arrangements, where one caregiver lives in the home on a flat daily or weekly rate instead of an hourly one.
Live-in care only works when the person can sleep through most of the night. The caregiver needs a private place to sleep and real rest. If your loved one wakes often at night, agencies usually switch to hourly shifts, and the cost climbs. Rules for live-in pay differ by state, so ask any agency to explain how they handle it.
What Makes the Price Go Up or Down?
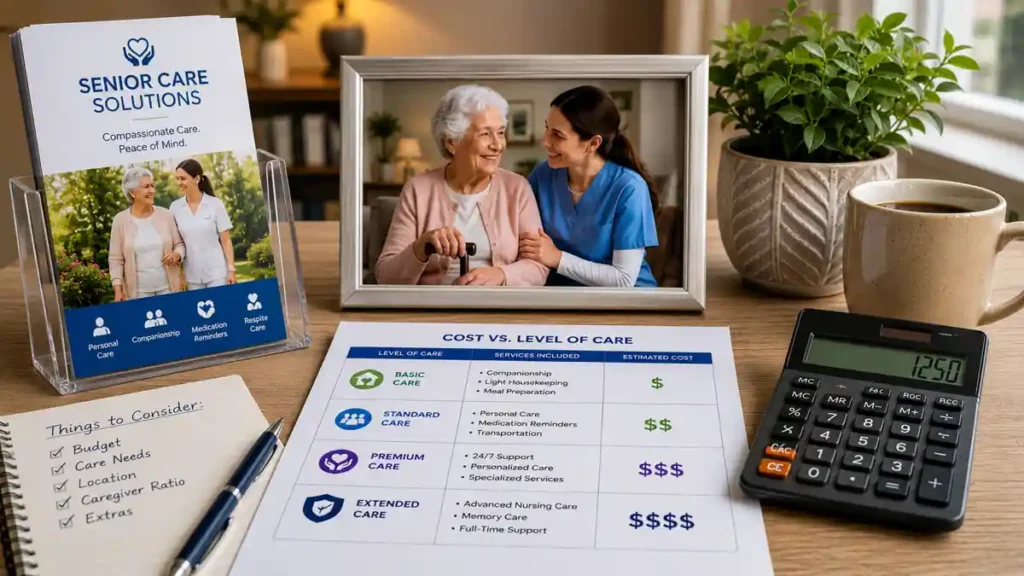
Where you live. Caregiver pay follows local wages and cost of living. A city aide typically costs more than one in a rural area.
How much help is needed. Companionship and meal prep sit at the base rate. Lifting and transfers, heavy incontinence care, and dementia supervision often cost more because they require extra training.
Agency or independent caregiver. An agency handles background checks, insurance, payroll, and backup staff when someone calls in sick. That convenience costs more. Hiring a caregiver directly is often cheaper per hour, but you become the employer. That means payroll taxes, workers’ compensation, and finding your own replacement on short notice. Many families check with a tax professional before going this route.
When care is needed. Overnights, weekends, and holidays often carry higher rates.
In-Home Care vs. Assisted Living
Home care is billed by the hour, so you pay only for the hours you use. Assisted living is a bundled monthly fee covering housing, meals, housekeeping, and shared staff. The CareScout survey puts the national median at about $6,200 a month.
That makes the crossover point easy to see. At roughly 20 to 30 hours of help a week, staying home is usually the cheaper option. Around 40 hours a week, home care costs about the same as assisted living. Beyond that, or when someone needs overnight supervision, assisted living or memory care often costs less.
Cost is only part of the decision, of course. Safety, loneliness, and what your loved one actually wants all matter just as much.
A small everyday tip: gentle movement helps people stay independent longer. Our guide to 10 Easy Chair Yoga Exercises for Seniors is a good place to start. And if a caregiver helps with cooking, our list of 12 Best Anti-Inflammatory Foods for Seniors can inspire easy, healthy meals.
How Families Pay for In-Home Care
Long-Term Care Insurance
If your parent bought a policy years ago, read it carefully. Most policies begin paying once a person needs hands-on help with two or more daily activities such as bathing, dressing, eating, or moving from bed to chair. Many also have an “elimination period,” often 30 to 90 days, during which the family pays out of pocket first.
VA Aid & Attendance
Aid & Attendance is an enhanced version of the VA’s needs-based pension. It is available to some wartime veterans and surviving spouses who need help with daily activities. The benefit is tax-free. The 2026 maximum monthly amounts are about:
- Single veteran: $2,424
- Veteran with a spouse: $2,874
- Surviving spouse: $1,558
These are maximums. The actual amount depends on countable income, and out-of-pocket medical and care costs can reduce that income. The 2026 net worth limit is $163,699, which counts assets plus annual income but generally excludes the primary home and one vehicle.
Important warning: The VA uses a 36-month look-back period. If assets were given away or transferred during that time to qualify, the VA can impose a penalty period of up to five years. Talk to a VA-accredited representative or an elder law attorney before moving any money. You can also start at VA.gov.
Medicaid Home and Community-Based Services (HCBS)
For families with limited income and assets, Medicaid is often the largest source of help. Every state runs its own Medicaid programs, and many offer “waivers” that pay for care at home instead of in a nursing facility. Eligibility rules differ widely, and some states have waiting lists. Your state Medicaid office or local Area Agency on Aging can tell you what is available where you live.
Area Agency on Aging
Every region in the U.S. has an Area Agency on Aging. These offices can point you to local programs, respite care, meal delivery, and caregiver support, often at low or no cost. The national Eldercare Locator will connect you with yours. It is one of the best free first calls a family can make.
Reverse Mortgages (HECM)
Homeowners age 62 or older with significant equity can use a Home Equity Conversion Mortgage to fund care at home. It reduces the equity left for heirs and involves closing costs, so speak with an independent, HUD-approved housing counselor first.
Adult Day Programs
Adult day health centers offer supervision, meals, activities, and health monitoring. The national median is about $95 per day. Two or three days a week can cut down on paid home hours while giving your loved one a social outlet and giving you a real break.
Possible Tax Benefits
Some families can deduct unreimbursed medical expenses, including certain care costs, if they itemize. Others may qualify for the dependent care credit. Rules are specific, so run this by a CPA.
What Medicare Covers (and Does Not)
This trips up almost everyone.
- Original Medicare does not pay for non-medical custodial care such as bathing, cooking, cleaning, or companionship when that is the only help needed.
- Medicare does cover short-term, doctor-ordered skilled home health care, such as nursing visits or therapy, when the patient is homebound and recovering from an illness, fall, or surgery.
- Some Medicare Advantage plans offer limited extra benefits, such as short-term in-home support after a hospital stay. These vary by plan and by year, so check the details of your specific plan.
You can read the official rules at Medicare.gov.
5 Questions to Ask Before Hiring an Agency
- Are caregivers employees of the agency? Ask whether they are bonded, insured, and background-checked.
- What is the minimum shift? Many agencies require 3 to 4 hours per visit.
- What happens if my caregiver is sick? Get the backup plan in writing.
- Do rates change for evenings, weekends, or holidays?
- Who reviews the care plan? Ask how often a nurse or care manager checks in as needs change.
Frequently Asked Questions
Does Medicare pay for in-home caregivers?
Not for everyday personal care. Original Medicare covers only short-term, doctor-ordered skilled care for people who are homebound.
Is a private caregiver cheaper than an agency?
Often, yes, because you are not paying agency overhead. But you take on employer duties like payroll taxes, insurance, and covering absences yourself.
How many hours should we start with?
Many families begin small, around 10 to 15 hours a week in a few short visits, and then adjust as needs change. Starting small also lets you see whether the caregiver is a good fit.
How can we keep costs manageable?
A mix often works best: family members cover what they can, an adult day program fills some weekdays, and a paid aide handles the hours no one else can. Check every benefit you might qualify for, too.
Sources and Further Reading
- CareScout Cost of Care Survey: national median rates for in-home care, adult day care, and assisted living.
- VA Aid and Attendance and Housebound Benefits: eligibility and rates.
- Medicare Home Health Services: what is and is not covered.
- Eldercare Locator (Administration for Community Living): find your local Area Agency on Aging.
Educational only — not medical, legal, or financial advice. Talk to a qualified professional before changing exercise, diet, medication, or making a major purchase. After60Guide is not a medical practice.
Gaurav Sharma is the founder and lead writer of After60Guide. He writes practical, source-cited guides on movement, nutrition, home safety, and everyday living after 60. He is not a doctor, physical therapist, or financial adviser. Health and money articles are general education, checked against official public sources where relevant — not personal advice. Corrections: contact@after60guide.com